Hilton Food Group, up 2.1%, announced the completion of the sale of its subsidiary, Dalco Food B.V., to Livekindly Production NL B.V., following the agreement announced on 31 July 2026.
Quartix Technologies, up 5.6%, in its trading statement for the nine months ended 30 September 2026, stated that annualised recurring revenue increased 11.0% to £39.70m, with net revenue retention of 97.3%. Subscriptions rose 7.0% to 347,702, while the customer base grew 6.0% to 33,873. Free cash flow for the period stood at approximately £4.70m, and the company held cash of £5.30m with no debt for the nine months ended 30 September 2026. It expects full-year revenue to be in line with market expectations, while adjusted profit is expected to be modestly ahead of market expectations. Separately, the company announced that BDO LLP has been appointed as auditor for the year ending 31 December 2026, following the resignation of PKF Littlejohn LLP. Netcall, up 1.2%, in its results for the year ended 30 June 2026, announced that revenue climbed to £57.70m from £47.96m recorded in the previous year. Profit before tax narrowed to £3.54m from £5.07m recorded in the prior year. Its cash and cash equivalents stood at £21.00m for the year ended 30 June 2026. The board has proposed a final dividend of 1.10p per share, payable on 8 February 2027 to shareholders on the register as at 29 December 2026.
Bango, down 5.4%, announced that LG U+, a leading telecommunications provider in South Korea with over 30m wireless subscriptions, has selected its Digital Vending Machine to expand the range of services available through its Udok subscription platform. The partnership will enable LG U+ to add global and local subscription services across streaming, lifestyle, AI and education, and to offer bundles, discounts and promotions to its customers.
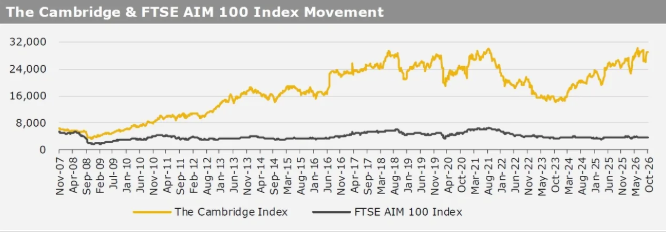
UK markets ended mostly higher last week, as government bond yields retreated. On the data front, UK’s construction PMI climbed more than expected in September. Meanwhile, the RICS housing price balance dropped in September. Moreover, the nation’s services PMI fell in September. The FTSE 100 index advanced 0.9% to settle at 10,552.1, while the FTSE AIM 100 index fell 0.9% to close at 3,597.3. Meanwhile, the FTSE techMARK 100 index gained 0.1% to end at 9,572.6.
US markets ended higher last week, as investors await quarterly corporate earnings reports. On the macro front, weekly jobless claims unexpectedly declined in the week ended 2 October 2026. Additionally, the S&P Global services PMI advanced more than expected in September. Meanwhile, US trade deficit widened more than expected in August, while the ISM services PMI unexpectedly dropped in September. Furthermore, the Michigan consumer sentiment index declined in October. The DJIA index rose 0.9% to end at 51,655, while the NASDAQ index gained 0.6% to close at 27,366.2.