Kier Group up 2.2%, in its trading update issued ahead of its Annual General Meeting, stated that trading had been in line with expectations and its enhanced medium-term financial targets. Its order book stood at £11.70b as at 30 September 2026 and is expected to grow by December 2026 following recent contract wins, including the approximately £600.00m Devonport 10 Dock programme.
Bango up 18.6% announced a group-level partnership with Ooredoo Group, a telecommunications provider serving nearly 150 million customers across nine markets in the Middle East, North Africa and Southeast Asia, giving its operating companies access to Bango’s Digital Vending Machine platform to bundle subscription services with mobile and fixed plans.
Cambridge Cognition Holdings up 5.5% announced the launch of its Winterlight speech assessment for academic researchers through the CANTAB Connect Research platform, having previously been available only through bespoke collaborations. The company stated that the move is intended to drive independent validation and wider adoption of speech-based cognitive assessment in drug development and healthcare.
Sareum Holdings down 3.3% announced that it will hold its Annual General Meeting (AGM) at 10:00 a.m. GMT on Wednesday, 16 December 2026 at the offices of ICR Healthcare, 85 Gresham Street, London EC2V 7NQ.
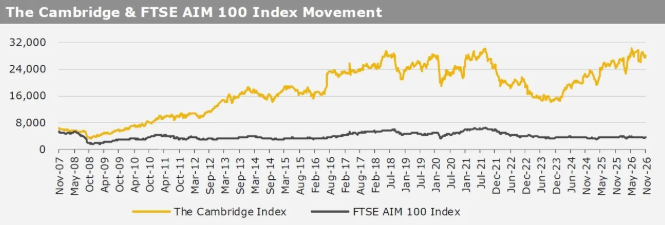
UK markets ended higher last week, as robust domestic economic growth data boosted investor sentiment. On the data front, UK’s gross domestic product (GDP) advanced as expected in 3Q26 Additionally, the nation’s industrial and manufacturing production both unexpectedly rose in September. Meanwhile, UK’s BRC like-for-like retail sales advanced less than forecasted in October. The FTSE 100 index advanced 2.1% to settle at 10,902.6, while the FTSE AIM 100 index rose 0.5% to close at 3,520.8. Additionally, the FTSE techMARK 100 index gained 1.0% to end at 9,413.0.
US markets ended higher in the previous week, as softer-than-expected US producer price inflation data eased concerns over aggressive Federal Reserve interest rate hikes. On the macro front, the US producer price index rose less than anticipated in October. Meanwhile, the US NFIB business optimism index dropped less than expected in October. Further, the US consumer price index advanced more than anticipated in October. Additionally, the US weekly jobless claims rose more than expected in the week ended 6 November 2026. The DJIA index rose 2.1% to end at 52,347.6, while the NASDAQ index gained 2.3% to close at 25,136.3.