(Kier Group PLC) Kier Group PLC, up 0.6%, announced that it has been appointed under a pre-construction services agreement with the UK Health Security Agency to deliver the H50 high-containment laboratory building at the UK Health Security Campus in Harlow, Essex, which forms part of a £3.52b programme. Early works are expected to begin in 2028, with main construction starting in 4Q29.
Netcall, up 0.8%, today, announced the appointment of Michael Potter as an Independent Non-Executive Director, effective 6 November 2026. LPA Group, unchanged at 82.0p, in its trading update for the year ended 30 September 2026, stated that revenue increased 30.0% to £28.10m. Order intake for the year stood at £20.70m, with the order book at £25.10m as at 30 September 2026. Adjusted earnings are expected to be in line with the guidance upgraded in September 2026, while reported profit before tax will include net exceptional income from an accelerated payment under an existing contract. Guidance for FY27 remains unchanged.
Sareum Holdings, down 44.5%, today, in its results for the year ended 30 June 2026, announced that operating loss widened to £3.72m from £3.38m recorded in the previous year. Cash and cash equivalents stood at £1.16m for the year ended 30 June 2026. Feedback, down 28.6%, announced that Queen Victoria Hospital NHS Foundation Trust has extended its Bleepa contract to the end of March 2027, worth £127,000, and has committed a further £249,000, awarded by Surrey and Sussex Integrated Care Board, for product development. The company expects its cash runway to extend to the end of the 1Q27 and stated that NHS England is now expected to begin a wider commissioning programme for clinical pathways in April 2027.
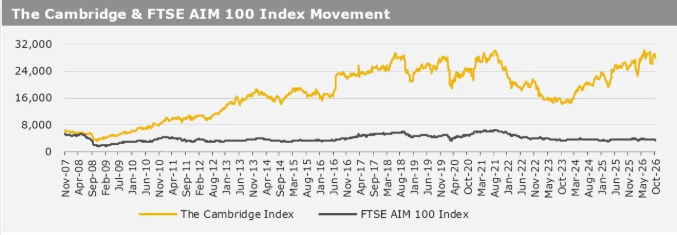
UK markets ended higher last week, after the government announced a smaller-than-expected increase in bank taxes in its annual budget. On the data front, UK’s BRC shop price index advanced more than expected in October. Meanwhile, UK’s nationwide housing prices index unexpectedly recorded a flat reading in October. The FTSE 100 index advanced 0.4% to settle at 10,729.8, while the FTSE AIM 100 index rose 1.1% to close at 3,472.0. Additionally, the FTSE techMARK 100 index gained 2.9% to end at 9,697.9.
US markets ended lower in the previous week, as disappointing technology earnings heightened investor concerns over substantial artificial intelligence spending. On the macro front, the Chicago PMI dropped more than forecasted in October. Additionally, the Federal Reserve (Fed) kept its key interest rate unchanged at 4.0% in its latest monetary policy meeting. Meanwhile, the US gross domestic product advanced more than anticipated in 3Q26, while the nation’s consumer confidence index unexpectedly climbed in October. Additionally, the US weekly jobless claims unexpectedly dropped in the week ended 23 October 2026. The DJIA index fell 0.9% to end at 51,770.3, while the NASDAQ index lost 2.0% to close at 25,437.0.